7 Mortgage Rate Forecasts for 2026: What to Expect
Table of Contents
- Understanding the Mortgage Landscape: A 2026 Overview
- Key Economic Influences on Mortgage Rates 2026 Forecast
- Expert Mortgage Rates 2026 Forecast Scenarios
- Factors Driving What Are Mortgage Rates Doing In 2026
- Preparing for the Mortgage Rates 2026 Forecast
- Strategic Planning for Your 2026 Mortgage Needs
- Actionable Steps: Your 2026 Mortgage Plan
- Conclusion: Navigating the Mortgage Rates 2026 Forecast
- FAQs About Mortgage Rates in 2026
The highly anticipated mortgage rates 2026 forecast suggests a complex interplay of economic forces shaping the housing market. Potential homeowners and those looking to refinance are keenly observing these predictions. Understanding the projected trajectory of interest rates will enable informed decisions regarding real estate investments and financial planning. Therefore, a comprehensive look at expert opinions is crucial for anyone engaging with the mortgage market in the coming years.
Understanding the Mortgage Landscape: A 2026 Overview
As we look towards the future, comprehending the mortgage rates 2026 forecast is essential for both buyers and existing homeowners. The housing market is dynamic, reflecting broader economic shifts. Many experts believe that while volatility may persist, a clearer picture will emerge.
The Current Economic Environment’s Impact
Presently, global economic indicators continue to influence domestic interest rates significantly. Inflation, employment figures, and central bank policies are direct drivers. Consequently, these elements will largely dictate what are mortgage rates doing in 2026. Moreover, geopolitical events can also introduce unexpected shifts, adding another layer of complexity to predictions.
For instance, persistent inflation could prompt central banks to maintain higher interest rates, impacting the mortgage rates 2026 forecast. Conversely, a cooling economy might lead to more favorable lending conditions. Therefore, staying informed about these macroeconomic trends is paramount.
Key Economic Influences on Mortgage Rates 2026 Forecast
Several fundamental economic factors will invariably guide the mortgage rates 2026 forecast. These aren’t isolated elements but rather interconnected aspects of the broader financial ecosystem. Consequently, monitoring these indicators provides valuable insights into future rate movements.
Inflationary Pressures and Federal Reserve Policy
Inflation remains a primary concern for policymakers and consumers alike. If inflation persists above target levels, the Federal Reserve will likely continue its restrictive monetary policy. This approach typically involves keeping the federal funds rate elevated, which indirectly pushes up mortgage rates. Therefore, the trajectory of inflation will profoundly influence the mortgage rates 2026 forecast.
- CPI Data: The Consumer Price Index (CPI) consistently measures inflation, providing key signals.
- PCE Index: The Personal Consumption Expenditures (PCE) price index is the Fed’s preferred inflation gauge.
- Fed Commentary: Statements from Federal Reserve officials offer direct clues about future policy.
Conversely, a significant drop in inflation could provide the Fed with room to ease policy, potentially leading to lower mortgage rates. Investors particularly watch the Fed’s decisions, as they directly influence bond yields, which subsequently affect mortgage pricing.
Economic Growth and Employment Data
A robust economy, characterized by strong GDP growth and low unemployment, often correlates with higher interest rates. Businesses expand, demand for credit increases, and inflationary pressures can build. Consequently, a strong economic outlook could mean a higher mortgage rates 2026 forecast.
Conversely, an economic slowdown or recession typically sees interest rates fall as central banks try to stimulate activity. Therefore, paying attention to monthly jobs reports and quarterly GDP releases offers critical insights into what are mortgage rates doing in 2026. A strong labor market, for example, signals economic resilience and might sustain higher rates.
Expert Mortgage Rates 2026 Forecast Scenarios
Analyzing predictions from various financial institutions offers a panoramic view of the possible mortgage rates 2026 forecast. Despite varying methodologies, common threads often emerge. These expert insights help homeowners and prospective buyers plan effectively.
Scenario 1: Moderate Decline in Rates
Many financial analysts foresee a moderate decline in mortgage rates throughout 2026. This scenario typically assumes that inflation will continue to cool, allowing the Federal Reserve to implement gentle rate cuts. Under this forecast, homeowners might see opportunities to refinance, and buyers could find slightly more affordable borrowing costs. Therefore, anticipating this trend is pivotal for financial planning.
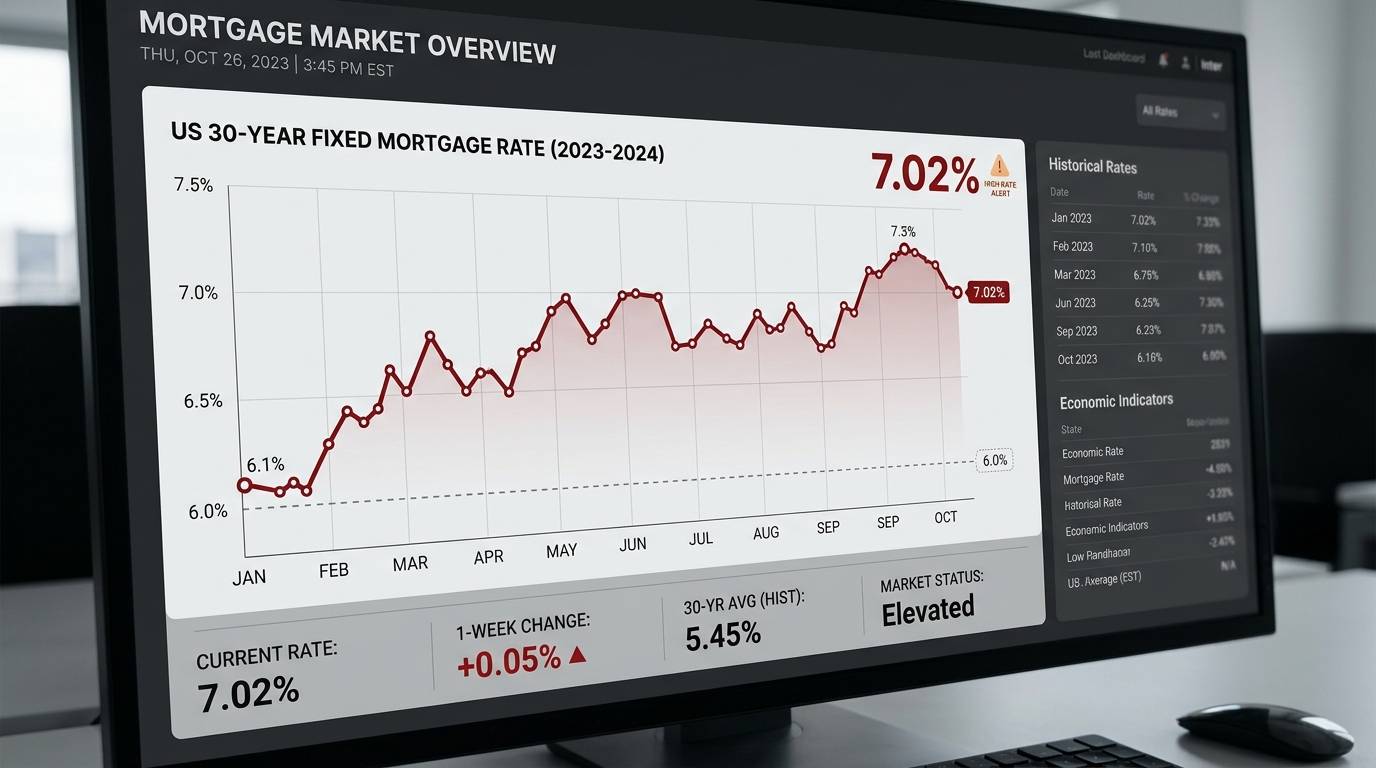
For instance, some economists predict average 30-year fixed mortgage rates might settle in the range of 5.5% to 6.5%. This would represent a significant easing from peak levels experienced in previous years. Such a decline would certainly influence the overall housing market activity, making homeownership more accessible.
Scenario 2: Rates Remain Elevated
Another prevalent mortgage rates 2026 forecast suggests that rates could remain elevated, possibly hovering near current levels or experiencing only marginal dips. This outlook often stems from concerns about persistent inflation or unforeseen economic resilience that keeps demand and borrowing costs high. Thus, preparedness for this scenario is equally important.
If rates stay high, say between 6.5% and 7.5%, homebuyers will continue to face affordability challenges. This situation emphasizes the importance of strong credit scores and larger down payments. Consequently, understanding what are mortgage rates doing in 2026 under this scenario helps in managing expectations and strategies. Finances News offers additional insights into market trends.
Scenario 3: Volatility and Unpredictability
A less optimistic but equally plausible mortgage rates 2026 forecast paints a picture of continued volatility. This scenario suggests frequent fluctuations driven by geopolitical events, unexpected economic data, or shifting central bank rhetoric. In such an environment, timing the market becomes exceedingly difficult.
Homebuyers might encounter periods of falling rates followed by sudden spikes, making quick decisions crucial. This volatility could also impact refinancing decisions. Therefore, flexibility and robust financial planning are key for anyone navigating such an unpredictable market.
Factors Driving What Are Mortgage Rates Doing In 2026
Beyond broad economic trends, specific elements directly influence the day-to-day fluctuations and long-term direction of mortgage rates. Understanding these nuances provides a more granular view of what are mortgage rates doing in 2026.
The Role of the Bond Market
The 10-year Treasury yield is often considered a benchmark for 30-year fixed mortgage rates. When bond yields rise, mortgage rates typically follow suit. This correlation is due to MBS (Mortgage-Backed Securities) being priced based on these yields. Therefore, tracking the bond market offers predictive power for the mortgage rates 2026 forecast.
- Treasury Auctions: The outcome of government bond auctions can move yields.
- Investor Demand: Global demand for U.S. debt impacts prices and yields.
- Economic Data: Strong or weak data can shift bond investor sentiment.
Conversely, a flight to safety during times of economic uncertainty can push bond yields down, potentially leading to lower mortgage rates. Consequently, monitoring global financial stability is also part of understanding the mortgage rates 2026 forecast.
Supply and Demand Dynamics in Housing
The fundamental principles of supply and demand significantly affect the housing market, indirectly influencing mortgage rates. A severe housing shortage, coupled with high demand, can inflate home prices. This can put additional pressure on affordability, even if rates decline.
If housing inventory increases significantly, however, it could stabilize or even lower prices, making housing more accessible. This, in turn, influences the overall demand for mortgages. Therefore, the balance between available homes and prospective buyers is a critical determinant of total market health and thus influences what are mortgage rates doing in 2026.
Preparing for the Mortgage Rates 2026 Forecast
Regardless of the specific mortgage rates 2026 forecast, proactive preparation is always the best strategy. This involves strengthening your financial position and understanding the various mortgage products available. Being prepared mitigates risks and maximizes opportunities.
Improving Your Credit Score
A higher credit score invariably translates to better loan terms, including lower interest rates. Lenders view borrowers with excellent credit as less risky. Therefore, focusing on improving your credit score should be a top priority if you plan to buy or refinance in 2026.
Steps to improve your credit include paying bills on time, reducing credit card debt, and checking your credit report for errors. Even a slight improvement can lead to substantial savings over the life of a mortgage. This is a crucial step towards securing a favorable mortgage rates 2026 forecast for your personal situation.
Saving for a Larger Down Payment
A substantial down payment reduces the amount you need to borrow, thereby decreasing your monthly payments and potentially allowing access to better interest rates. It also shows lenders that you are a serious and financially stable borrower. The more money you put down upfront, the less risk the lender takes.
Furthermore, a larger down payment can help you avoid Private Mortgage Insurance (PMI) if you put down 20% or more. This represents a significant saving each month, making your overall mortgage more affordable. Planning to save aggressively can put you in a very strong position when considering what are mortgage rates doing in 2026.
Strategic Planning for Your 2026 Mortgage Needs
With an understanding of the mortgage rates 2026 forecast, strategic planning becomes paramount. This involves evaluating different mortgage types and considering the broader implications for your financial portfolio. Thoughtful selection of a mortgage product can yield significant benefits.
Evaluating Fixed-Rate vs. Adjustable-Rate Mortgages
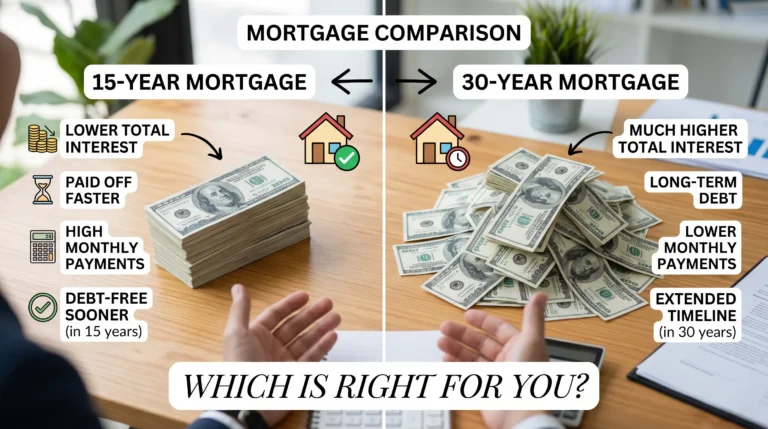
The choice between a fixed-rate mortgage (FRM) and an adjustable-rate mortgage (ARM) depends heavily on the prevailing mortgage rates 2026 forecast and your personal risk tolerance. A fixed-rate mortgage offers stability, with a consistent payment for the life of the loan, regardless of market fluctuations.
Conversely, an ARM typically starts with a lower interest rate, which adjusts after an initial fixed period. If rates are expected to fall, an ARM might seem attractive, but it carries the risk of higher payments if rates rise. Therefore, carefully consider the long-term outlook when deciding what are mortgage rates doing in 2026 and how they might affect each option.
| Feature | Fixed-Rate Mortgage | Adjustable-Rate Mortgage (ARM) |
|---|---|---|
| Interest Rate Stability | Fixed for loan term | Adjusts periodically after initial fixed period |
| Initial Monthly Payment | Typically higher | Often lower |
| Payment Predictability | High | Low after fixed period |
| Interest Rate Risk | Low (borrower) | High (borrower) |
| Best for | Long-term stability; rising rate environment | Short-term ownership; falling rate environment |
| Refinance Potential | Less likely if rates fall substantially | More likely if rates rise substantially |
Impact of Geopolitical Stability on Mortgage Rates 2026 Forecast
Global events, such as international conflicts or significant trade disputes, can introduce substantial uncertainty into financial markets. This uncertainty often leads investors to seek safe-haven assets, like U.S. Treasury bonds. An increased demand for bonds can drive down their yields, which, counter-intuitively, might lead to lower mortgage rates. However, extreme instability could also lead to risk aversion and tighter credit, negatively impacting the mortgage rates 2026 forecast.
Therefore, staying informed about global affairs is a subtle yet important aspect of anticipating what are mortgage rates doing in 2026. These external factors can quickly override domestic economic trends, creating unexpected shifts in the market. Wikipedia offers a detailed overview of mortgage financing.
Actionable Steps: Your 2026 Mortgage Plan
Developing a concrete plan is crucial for navigating the projected mortgage rates 2026 forecast. These steps will help you prepare financially and strategically for any market conditions.
Step 1: Get Pre-Approved for a Mortgage
A mortgage pre-approval is more than just an estimate; it’s a conditional commitment from a lender. This process involves a thorough review of your financial standing, giving you a clear picture of how much you can afford. It also shows sellers that you are a serious buyer, which can be a significant advantage in a competitive market.
Getting pre-approved early allows you to understand your budget within the context of the mortgage rates 2026 forecast. You can compare offers from different lenders and identify the best rates available to you. Utilize free financial calculators to estimate potential mortgage payments.
Step 2: Monitor Market Trends Continuously
The mortgage market is constantly evolving, and rates can change daily. Therefore, consistent monitoring of economic news and financial forecasts is vital. Subscribe to financial news outlets, follow reputable economic analysts, and keep an eye on key indicators like inflation and unemployment reports.
- Set Rate Alerts: Many financial websites offer email alerts when rates hit a certain threshold.
- Consult Experts: Speak regularly with mortgage brokers and financial advisors.
- Review Economic Data: Pay attention to CPI, PCE, and jobs reports.
Being informed will enable you to act swiftly if favorable conditions emerge, especially concerning your personal mortgage rates 2026 forecast. This can be the difference between securing an excellent rate and missing an opportunity.
Step 3: Build a Financial Buffer
Regardless of what are mortgage rates doing in 2026, having a robust emergency fund is always a smart financial move. Unexpected expenses can arise, and a financial buffer ensures you can meet your mortgage payments even if your income fluctuates or other costs increase. Aim for at least 3-6 months of living expenses saved in an accessible account.
This financial stability not only provides peace of mind but also strengthens your overall financial profile, which can indirectly benefit your mortgage applications. It provides a cushion against potential economic downturns or personal financial setbacks, securing your investment in a home.
Step 4: Explore Different Loan Programs
Beyond traditional fixed and adjustable-rate mortgages, various loan programs cater to different needs. For example, FHA loans, VA loans, and USDA loans offer unique benefits, such as lower down payments or more flexible credit requirements. Researching these options can reveal paths to homeownership you might not have considered.
Understanding each program’s eligibility criteria and benefits is crucial. What might be the best option for one person considering the mortgage rates 2026 forecast might not be ideal for another. Always compare terms, fees, and long-term costs. You can find more specific guidance on car and auto finance guides which often discuss broader loan principles.
Step 5: Consider Your Refinancing Options
For existing homeowners, the mortgage rates 2026 forecast offers potential opportunities for refinancing. If rates fall significantly, refinancing could lower your monthly payments, reduce your loan term, or allow you to tap into your home equity. However, evaluating the costs associated with refinancing against the potential savings is crucial.
Always perform a break-even analysis to determine how long it will take to recoup your closing costs. This will help you decide if refinancing is a financially sound decision given what are mortgage rates doing in 2026. A detailed analysis ensures that your refinancing strategy aligns with your long-term financial goals.
Conclusion: Navigating the Mortgage Rates 2026 Forecast
In summary, the mortgage rates 2026 forecast presents a mixed but generally optimistic outlook, with possibilities ranging from moderate declines to continued stability or even some volatility. Key economic indicators such as inflation, Federal Reserve policy, and overall economic growth will be pivotal in shaping these rates. Understanding what are mortgage rates doing in 2026 requires continuous monitoring of these complex interdependencies. While predictions vary, proactive financial planning remains the most effective strategy for both prospective homeowners and those looking to refinance. By strengthening your credit, saving diligently, exploring all loan options, and staying informed, you can confidently navigate the mortgage landscape and make the most of the opportunities that 2026 may bring. Ultimately, your personal financial readiness will be the most significant factor in securing favorable mortgage terms, regardless of the broader market trends.
What factors will most influence the mortgage rates 2026 forecast?
The primary influences on the mortgage rates 2026 forecast will be inflation rates, the Federal Reserve’s monetary policy decisions, and the overall health of the U.S. economy, including employment and GDP growth.
Should I wait for 2026 to buy a home if I anticipate lower rates?
Deciding when to buy depends on various personal and market factors, not solely on the mortgage rates 2026 forecast. While some forecasts suggest potential rate dips, waiting carries the risk of home price appreciation, which could offset any savings from lower interest rates. Consult a financial advisor for personalized guidance.
How can I prepare for the mortgage rates 2026 forecast?
To prepare for the mortgage rates 2026 forecast, focus on improving your credit score, saving for a larger down payment, getting pre-approved for a mortgage, and continuously monitoring market trends. This strategy helps ensure you secure the best possible terms.
What are mortgage rates doing in 2026 if inflation stays high?
If inflation remains persistently high, it is likely that the Federal Reserve would maintain higher interest rates or even increase them further. This scenario could lead to elevated mortgage rates in 2026, making borrowing more expensive.
Will adjustable-rate mortgages (ARMs) be a good option given the mortgage rates 2026 forecast?
The attractiveness of ARMs in 2026 depends heavily on the specific mortgage rates 2026 forecast. If rates are predicted to fall or remain stable for an extended initial period, an ARM might offer lower initial payments. However, if rates rise after the fixed period, payments could increase significantly. Evaluate your risk tolerance carefully.