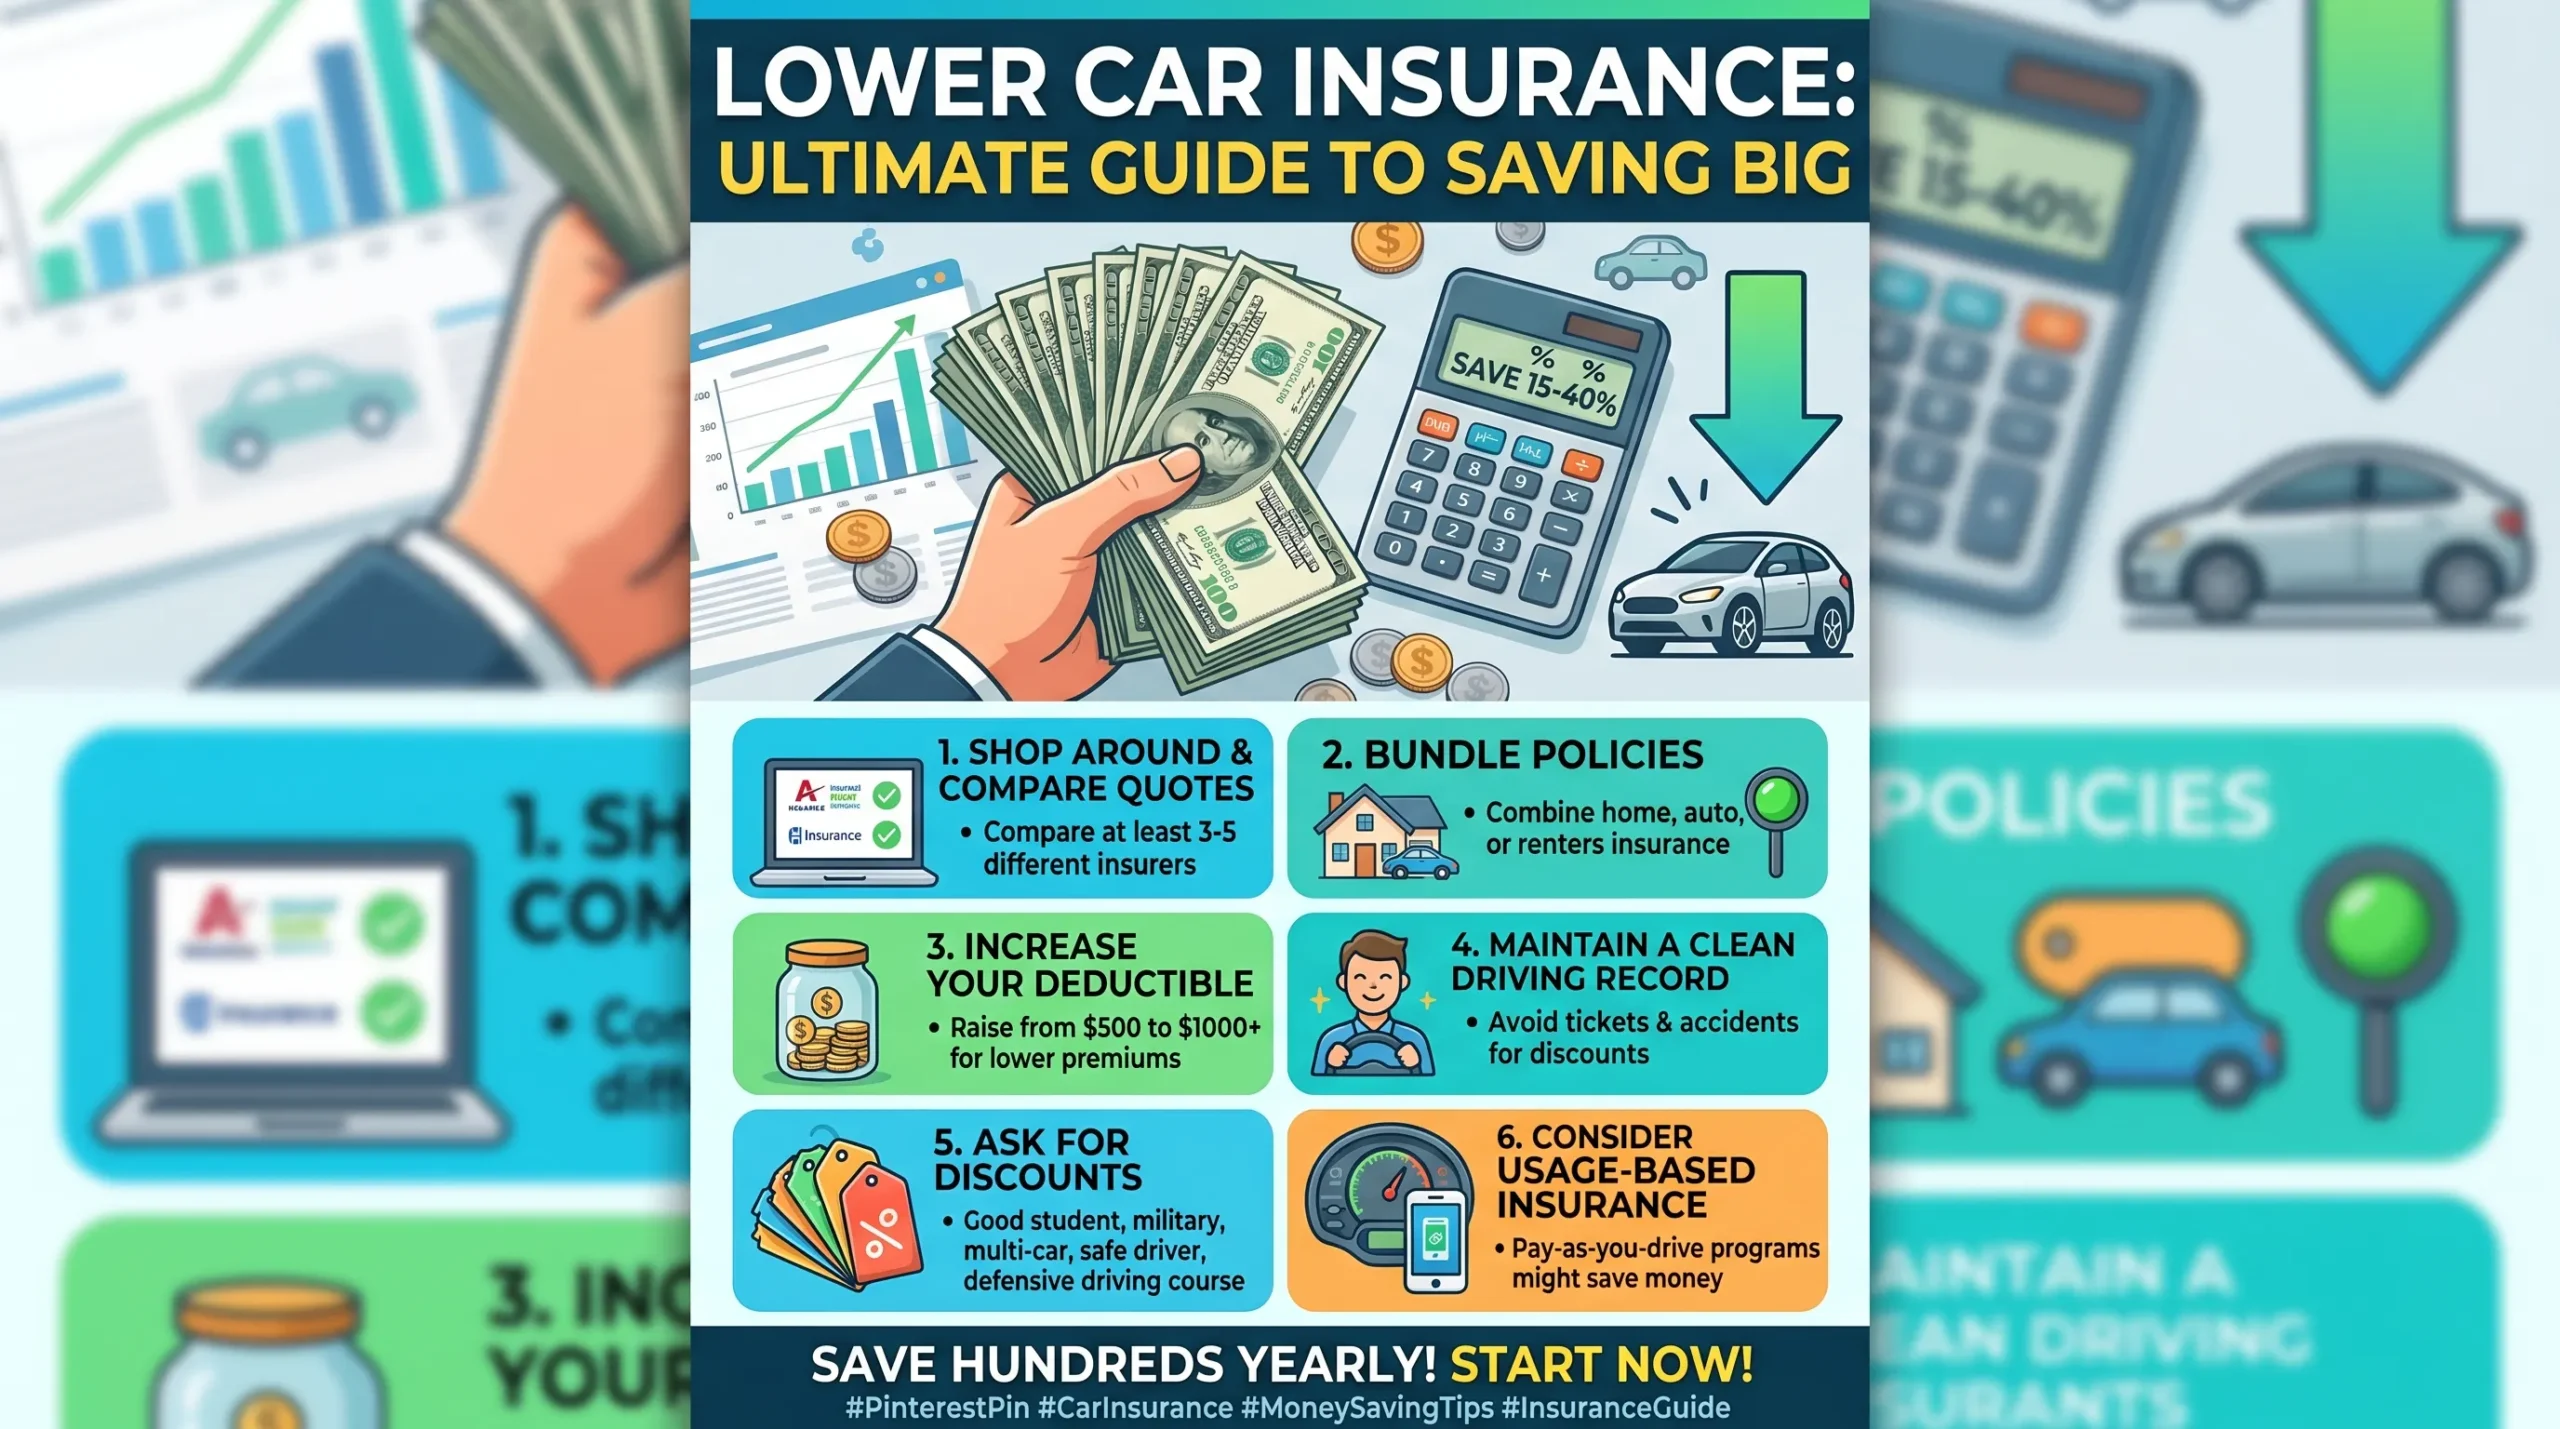
Lower Car Insurance: Ultimate Guide to Saving Big
Table of Contents
- Understanding Your Car Insurance Policy
- Immediate Steps to Lower Car Insurance Costs
- Strategic Decisions to Lower Car Insurance Long-Term
- Harnessing Discounts to Lower Car Insurance Significantly
- Comparing Insurers and Policies to Lower Car Insurance
- Action Plan: How to Lower Car Insurance Premiums Today
- Conclusion: Your Path to Lower Car Insurance
- FAQs About How to Lower Car Insurance Premiums
Learning how to lower car insurance rates is a top priority for many drivers, especially as costs continue to fluctuate. In fact, understanding the levers you can pull to reduce your premiums can lead to substantial savings each year. This comprehensive guide will equip you with expert insights and actionable strategies to significantly cut down your auto insurance expenses, ensuring you get the best coverage without overpaying. We’ll delve into everything from policy adjustments to long-term habits that positively impact your rates, making it easier to lower car insurance effectively.
Understanding Your Car Insurance Policy
Before you can successfully lower car insurance, you must first grasp the components of your current policy. Essentially, knowing what you pay for is the first step toward reducing those costs. Car insurance policies generally consist of several key coverages, each impacting your premium.
Defining Key Coverage Types
Firstly, liability coverage is mandated in almost every state; it covers damages and injuries you cause to others. Collision coverage, on the other hand, pays for damage to your own vehicle from an accident. Comprehensive coverage protects against non-collision incidents like theft, vandalism, or natural disasters. Furthermore, personal Injury Protection (PIP) or medical payments coverage handles medical expenses for you and your passengers after an accident. Understanding these helps you identify areas where you might adjust to lower car insurance.
Ultimately, assessing your needs for each type of coverage can reveal opportunities. For instance, if you drive an older car with low market value, dropping collision or comprehensive coverage might be a wise decision to lower car insurance costs. Many drivers overpay because they carry coverage that no longer serves their financial situation.
Immediate Steps to Lower Car Insurance Costs
There are several quick adjustments you can make to immediately begin to lower car insurance premiums. These strategies often involve direct conversations with your current insurer or quick financial decisions.
Review and Adjust Your Deductibles
One of the most straightforward ways to how to lower car insurance premiums is by increasing your deductible. Your deductible is the amount you pay out-of-pocket before your insurance kicks in. A higher deductible typically results in a lower premium, because you’re taking on more financial responsibility for minor claims.
- Assess your emergency fund: Ensure you have sufficient savings to cover a higher deductible if necessary.
- Calculate potential savings: Ask your insurer how much you’d save by increasing your deductible from, say, $500 to $1,000 or even $2,500.
- Consider your claim history: If you rarely file claims, a higher deductible might be a smart move to lower car insurance.
For example, if increasing your deductible saves you $200 a year and you only claim every five years, you’ve saved $1,000 against a single $500 higher deductible payout. This is a common tactic to lower car insurance for many prudent drivers.
Eliminate Unnecessary Coverages
Moreover, scrutinize your policy for any coverages you no longer need. For instance, if you have roadside assistance or rental car reimbursement from another source, like your auto manufacturer or a credit card, you can likely remove these from your policy. Additionally, for older vehicles, especially those worth less than 10 times your annual premium for collision and comprehensive, it often makes financial sense to drop these coverages entirely. This change can significantly lower car insurance.
Periodically, revisit your policy to ensure you’re not paying for redundant or irrelevant protections. This simple review can reveal surprising areas to lower car insurance.
Strategic Decisions to Lower Car Insurance Long-Term
Beyond immediate adjustments, certain long-term strategic choices can substantially lower car insurance over time. These often involve lifestyle changes or purchasing decisions.
Maintain a Clean Driving Record
Undeniably, one of the most impactful ways to lower car insurance is by maintaining a spotless driving record. Accidents and traffic violations, especially serious ones, can drastically increase your premiums for several years. Insurers view safe drivers as lower risk, thus rewarding them with better rates.
- Avoid speeding tickets: Even minor infractions can add points to your license.
- Drive defensively: Reduce your risk of accidents by being proactive and aware on the road.
- Attend defensive driving courses: Some insurers offer discounts for completing approved courses, especially after a minor infraction, helping to lower car insurance.
Ultimately, a clean record not only saves you money on insurance but also protects you from the inconvenience and stress of accidents.
Choose Your Vehicle Wisely
The type of car you drive plays a significant role in how to lower car insurance premiums. Generally, vehicles that are expensive to repair, powerful, or frequently stolen tend to have higher insurance rates. Before purchasing a new vehicle, research its insurance costs.
For instance, statistics show that luxury cars, sports cars, and certain SUVs usually come with heftier premiums. Conversely, vehicles with high safety ratings and lower repair costs often lead to lower car insurance premiums. Furthermore, installing anti-theft devices can also lead to discounts, further helping to lower car insurance.
Improve Your Credit Score
In many states, insurance companies use a credit-based insurance score as a factor in determining premiums. A higher credit score often indicates financial responsibility, which insurers associate with a lower likelihood of filing claims. Consequently, improving your credit score can be a powerful long-term strategy to lower car insurance.
For more detailed insights on managing your finances, explore Finances News.
Harnessing Discounts to Lower Car Insurance Significantly
Many drivers overlook the vast array of discounts available that can dramatically how to lower car insurance premiums. It’s crucial to actively ask your insurer about all possible discounts you might qualify for.
Commonly Available Discounts
Insurance companies offer numerous discounts, and combining several can lead to significant savings. Here’s a breakdown of some prominent ones:
- Bundling discounts: Purchase multiple policies (e.g., auto and home) from the same insurer to receive a discount.
- Good student discounts: Students with a certain GPA (typically B average or higher) often qualify.
- Multi-car discounts: Insuring more than one vehicle with the same company usually results in a price break.
- Low mileage discounts: If you drive fewer miles annually than the average, you might be eligible.
- Safe driver discounts: Rewarded for having no accidents or violations for a certain period.
- Usage-based insurance discounts: Telematics programs track your driving habits (speed, braking, etc.) and reward safe driving with lower rates.
- Anti-theft device discounts: Alarms, tracking devices, and immobilizers can reduce premiums.
- Paid-in-full discount: Paying your annual premium upfront instead of monthly installments often saves money.
- Driver’s education/defensive driving course discount: Completing approved courses can lead to a reduction.
It’s always worth a thorough conversation with your insurance agent to exhaust all possibilities to lower car insurance through discounts.
Table: Potential Car Insurance Discount Savings (2026 Estimates)
| Discount Type | Estimated Savings Range | Conditions/Notes |
|---|---|---|
| Bundling (Auto + Home) | 5% – 25% | Varies by insurer and policy combination |
| Good Student | 10% – 25% | 學生 must maintain GPA (e.g., 3.0+), under 25 years old |
| Multi-Car | 10% – 25% (per car) | All vehicles insured under one policy, same household |
| Low Mileage | 5% – 20% | Typically under 7,500 – 10,000 miles per year |
| Safe Driver/Accident-Free | 10% – 40% | Period varies (e.g., 3-5 years accident-free) |
| Usage-Based Insurance (Telematics) | 5% – 30% | Requires installing a device or app; based on driving behavior |
| Anti-Theft Device | 5% – 15% | Alarm systems, GPS tracking, immobilizers |
| Paid-in-Full | 5% – 10% | Paying annual premium upfront avoids installment fees |
| Defensive Driving Course | 5% – 10% | State-approved course completion, often for older drivers or after violations |
These figures are estimates for 2026 and can vary significantly by insurance provider, location, and individual driving profile. Nevertheless, they illustrate the potential to lower car insurance premiums.
Comparing Insurers and Policies to Lower Car Insurance
One of the most effective strategies to lower car insurance is to shop around and compare quotes from multiple providers regularly. Loyalty to one insurer doesn’t always pay off; rates can vary widely between companies for the same coverage.
Get Multiple Quotes Annually
It’s advisable to get new quotes at least once a year, or whenever major life events occur. Events like moving, getting married, buying a new car, or adding a new driver to your policy are excellent times to reassess your insurance needs and shop for better rates. This proactive approach can significantly how to lower car insurance premiums.
- Utilize online comparison tools: Many websites allow you to quickly compare quotes from numerous insurers.
- Contact independent agents: These agents work with multiple companies and can find the best rates for you.
- Directly contact major insurers: Speak with representatives from major carriers who might offer exclusive deals.
Remember that the cheapest option isn’t always the best; always compare coverage limits, deductibles, and customer service reviews alongside the premium. The goal is to lower car insurance without sacrificing necessary protection.
Re-evaluate Your Policy Periodically
Life changes, and so should your insurance policy. Regular review ensures you’re adequately covered without overpaying. For example, if your daily commute distance decreases, or if you now work from home, that change could lead to a lower car insurance premium as your risk profile changes.
Furthermore, removing a driver who no longer lives in your household or upgrading your vehicle’s safety features should prompt a review. These actions directly contribute to your ability to lower car insurance costs.
Action Plan: How to Lower Car Insurance Premiums Today
To summarize, here’s a step-by-step action plan to effectively how to lower car insurance premiums.
- Review Your Current Policy: Understand all coverages, deductibles, and any add-ons you currently have. Identify any redundancies or unnecessary protections to lower car insurance.
- Increase Your Deductible: If your emergency fund allows, raising your deductible can instantly reduce your premium. This is a powerful step to lower car insurance.
- Ask About All Available Discounts: Directly ask your insurer about every single discount they offer. Don’t assume they’ll proactively apply them. Reference our table above for ideas.
- Maintain a Clean Driving Record: Commit to safe driving habits. This is a long-term investment that definitely helps lower car insurance.
- Shop Around for Quotes: Obtain quotes from at least 3-5 different insurance providers. Use comparison websites, independent agents, and direct insurers to compare. This is arguably the most impactful way to lower car insurance.
- Improve Your Credit Score: Work on financial habits that boost your credit score, as this can lead to better rates in many states. For more practical tools, visit our free financial calculators.
- Consider Usage-Based Insurance: Enroll in telematics programs if you’re a safe driver. This is a direct path to lower car insurance by proving your low-risk profile.
- Choose Your Next Vehicle Wisely: When buying a new car, research its insurance costs beforehand. Opt for models known for lower insurance premiums. For more insights on vehicle financing and related topics, explore our detailed car and auto finance guides.
- Bundle Your Policies: If you have home, renter’s, or other insurance policies, try to bundle them with one provider for a multi-policy discount.
By diligently following these steps, you are well on your way to securing a much better rate and will indeed lower car insurance.
Conclusion: Your Path to Lower Car Insurance
Ultimately, taking control of your car insurance costs can lead to significant savings. By understanding your policy, making smart adjustments, maintaining good driving habits, and diligently shopping around, you can effectively lower car insurance premiums. Remember, your insurance needs evolve, so regular review and comparison are key. Don’t settle for high premiums when there are so many strategies available to you. Start implementing these tips today to secure a more affordable auto insurance policy. You certainly have the power to lower car insurance substantially with these tools and information.
FAQs About How to Lower Car Insurance Premiums
What is the single most effective way to lower car insurance?
The most effective way to lower car insurance for many drivers is to shop around and compare quotes from at least 3-5 different insurance providers annually. Rates vary significantly, and new providers might offer better deals even for the exact same coverage.
Does driving less help lower car insurance?
Yes, driving fewer miles generally helps lower car insurance. Many insurers offer ‘low mileage’ discounts, and some even provide usage-based insurance programs (telematics) that track your actual mileage and driving habits, rewarding less time on the road with lower premiums.
Can simply asking my insurer help me lower car insurance?
Absolutely. Many people fail to realize they qualify for various discounts. By directly asking your insurer about all available discounts and reviewing your policy with them, you can often discover opportunities to lower car insurance that you weren’t aware of.
How does my credit score affect my ability to lower car insurance?
In many states, insurance companies use a credit-based insurance score to help determine your premium. A higher credit score often signals financial responsibility, which insurers associate with a lower risk of filing claims. Therefore, improving your credit score can significantly help to lower car insurance.
Is it always better to choose a higher deductible to lower car insurance?
Choosing a higher deductible almost always results in a lower car insurance premium. However, it’s only ‘better’ if you have an adequate emergency fund to cover that higher deductible in the event of a claim. Always ensure you can comfortably afford the deductible before making this change to lower car insurance.