7 Steps to Build an Emergency Fund That Protects You
Table of Contents
- Introduction: Your Essential Emergency Fund Guide
- Understanding the Importance of an Emergency Fund Guide
- Step 1: Define Your Financial Benchmark with Our Emergency Fund Guide
- Step 2: Set Realistic Savings Goals for Your Emergency Fund Guide
- Step 3: Optimize Your Budget for an Emergency Fund Guide
- Step 4: Automate Your Savings for an Emergency Fund Guide
- Step 5: Choose the Right Savings Vehicle for Your Emergency Fund Guide
- Step 6: Boost Your Fund with Extra Income
- Step 7: Revisit and Replenish Your Emergency Fund Guide
- Action Plan: How to Build Emergency Fund Effectively
- Conclusion: Securing Your Future with an Emergency Fund Guide
- FAQs About Your Emergency Fund Guide
Our comprehensive emergency fund guide provides 7 crucial steps to building a robust financial safety net. Unexpected expenses can derail even the most carefully planned budgets. Therefore, having accessible funds is absolutely vital for financial stability. This guide will walk you through the process, ensuring you know how to build emergency fund that truly protects you from life’s curveballs. We’ll explore practical strategies and actionable advice to help you establish and maintain your financial buffer.
Understanding the Importance of an Emergency Fund Guide
An emergency fund is more than just a savings account; it’s a shield against unforeseen financial shocks. Indeed, this essential emergency fund guide emphasizes its role in preventing debt. When unexpected events like job loss, medical emergencies, or car repairs occur, an adequately funded emergency reserve protects your existing investments and credit score. Without one, you might resort to high-interest credit cards or loans, digging yourself into a deeper financial hole. Consequently, understanding this importance is the first step in our emergency fund guide.
Why Every Household Needs an Emergency Fund
Every household, regardless of income level, benefits profoundly from an emergency fund. For instance, life’s unpredictability demands a financial safety net. A job loss can lead to months without income, while a sudden health issue can incur significant out-of-pocket costs. This emergency fund guide stresses that an emergency fund provides peace of mind. It allows you to navigate these difficult times without sacrificing your long-term financial goals or falling into debt. Therefore, building this fund is a cornerstone of responsible financial planning, as highlighted in this emergency fund guide.
Step 1: Define Your Financial Benchmark with Our Emergency Fund Guide
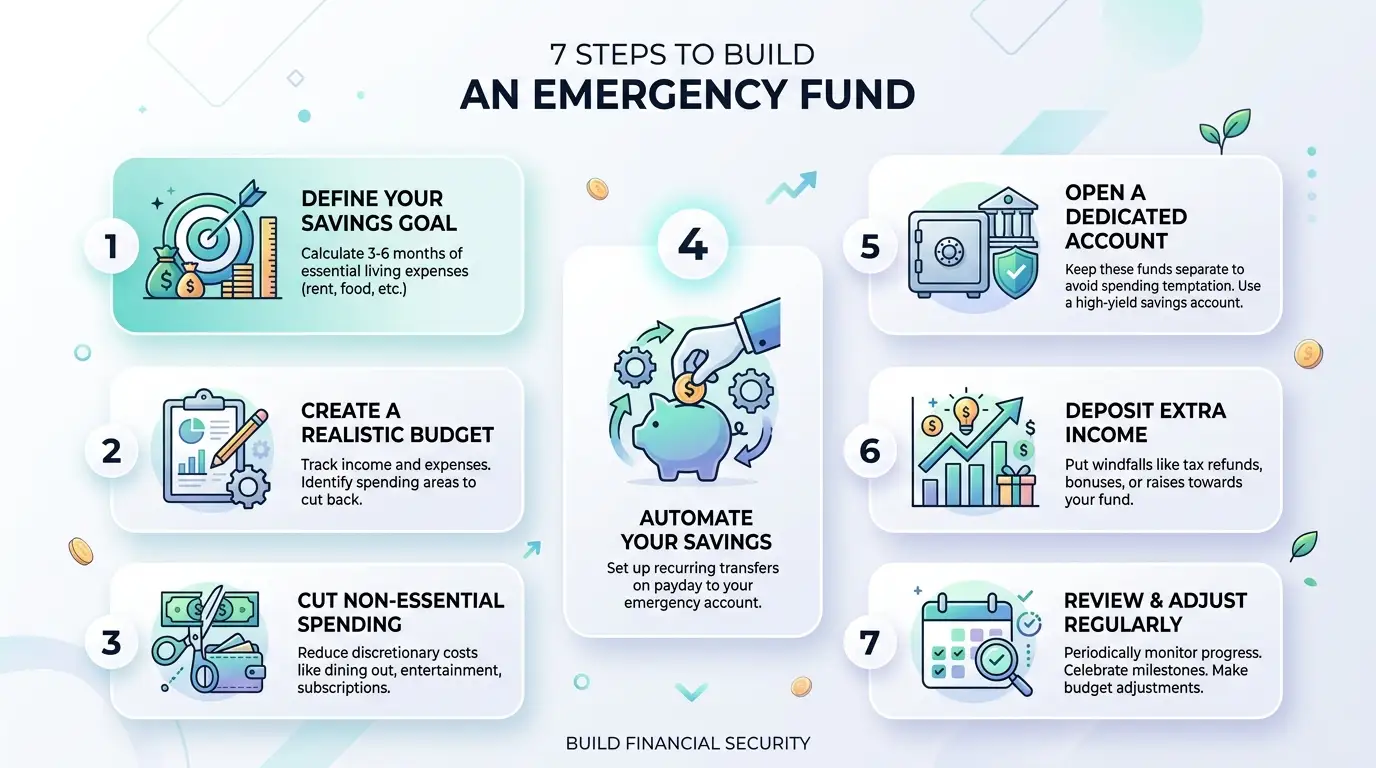
The very first step in this emergency fund guide is to determine how much money you actually need. Generally, financial experts recommend having three to six months’ worth of essential living expenses saved. This crucial benchmark varies depending on your personal circumstances. Factors like job security, health, and family size all play a role. Ultimately, this specific emergency fund guide will help you tailor that amount to your unique situation. Therefore, accurately calculating your monthly expenses is paramount to knowing how to build emergency fund effectively.
Calculating Your Essential Monthly Expenses
To accurately define your financial benchmark, list all your non-negotiable monthly expenses. These include housing (rent/mortgage), utilities, food, transportation, insurance premiums, and minimum debt payments. Discretionary spending like dining out or entertainment should not be included for this calculation. Our emergency fund guide suggests reviewing your bank statements and budgeting apps over several months to get a clear picture. This precise calculation forms the foundation of your emergency fund goals. Certainly, this meticulous approach is key to an effective emergency fund guide.
Step 2: Set Realistic Savings Goals for Your Emergency Fund Guide
Once you know your target amount, the next step is to set achievable savings goals. Breaking down a large sum into smaller, manageable targets makes the process less daunting. Indeed, this practical emergency fund guide advocates for incremental progress. For example, aim to save $500 in the first month, then consistently increase that amount. Setting realistic goals prevents frustration and helps you maintain momentum. This thoughtful strategy is a core component of how to build emergency fund successfully.
Breaking Down Your Emergency Fund Goal
Consider dedicating a specific amount each month towards your emergency fund. If your goal is $10,000, and you aim to achieve it in 12 months, you’d need to save approximately $833 per month. Adjust this based on your current income and expenses. This emergency fund guide recommends starting small if necessary and gradually increasing your contributions. Consistency is more important than the absolute amount, especially initially. For further assistance, check out our free financial calculators.
Step 3: Optimize Your Budget for an Emergency Fund Guide
Optimizing your budget is essential for freeing up money to save. This strategic emergency fund guide strongly recommends a thorough review of your current spending habits. Identify areas where you can reduce expenses without significantly impacting your quality of life. Even small cuts can add up over time. Ultimately, this step directly contributes to knowing how to build emergency fund efficiently and quickly.
Identifying Areas for Spending Cuts
Start by scrutinizing your variable expenses. For instance, can you reduce your grocery bill by meal planning? Are there subscriptions you no longer use? Can you cut back on impulse purchases? Even seemingly insignificant changes, like opting for coffee at home instead of daily cafe visits, can contribute substantially. Our emergency fund guide encourages you to track every dollar spent for a month. This can reveal unexpected areas for savings. Budgeting is a powerful tool to redirect funds towards your emergency fund guide.
Step 4: Automate Your Savings for an Emergency Fund Guide
Automation is arguably the most effective strategy for building an emergency fund. Setting up automatic transfers ensures consistent contributions without relying on willpower. This crucial emergency fund guide emphasizes its simplicity and efficacy. Once it’s set up, you won’t even have to think about it! Therefore, automating your savings streamlines the process of knowing how to build emergency fund.
Setting Up Automatic Transfers
Arrange for a fixed amount to be transferred from your checking account to your dedicated emergency fund savings account on payday. Treat this transfer as a non-negotiable bill. Even a small initial amount, like $25 or $50, can kickstart your savings. You can always increase it later as your financial situation improves. Our emergency fund guide champions this method for its reliability and ease of use. This consistent flow is vital for building your emergency fund guide.
Comparison: Savings Account Options for Your Emergency Fund in 2026
Choosing the right account for your emergency fund is crucial. Here’s a comparison of common options available in 2026:
| Account Type | Average APY (2026) | Liquidity (Access) | Safety (FDIC/NCUA) | Best For |
|---|---|---|---|---|
| High-Yield Savings Account (HYSA) | 4.50% – 5.15% | High (Instant) | Yes | Primary Emergency Fund, earning competitive interest. |
| Money Market Account (MMA) | 4.25% – 4.90% | High (Checks, Debit Card) | Yes | Larger Emergency Fund with check-writing convenience. |
| Traditional Savings Account | 0.01% – 0.50% | High (Instant) | Yes | Beginners, but very low returns. Not ideal for growth. |
| Certificate of Deposit (CD) | 4.00% – 5.50% | Low (Penalty for early withdrawal) | Yes | Funds for defined future goals, NOT emergencies. |
Step 5: Choose the Right Savings Vehicle for Your Emergency Fund Guide
Where you store your emergency fund matters significantly. The ideal account offers both liquidity and safety. This vital emergency fund guide recommends high-yield savings accounts (HYSAs) for exactly these reasons. They provide easy access to your money while also earning a competitive interest rate. Selecting the correct account is integral to knowing how to build emergency fund effectively.
High-Yield Savings Accounts vs. Other Options
Unlike traditional savings accounts with paltry interest rates, HYSAs typically offer much higher annual percentage yields (APYs). This means your money grows faster. Importantly, they are FDIC-insured up to $250,000, ensuring your principal is safe. Avoid investing your emergency fund in volatile assets like stocks, as you need guaranteed access to the principal amount when an emergency strikes. Our emergency fund guide emphasizes safety and accessibility above all. This choice is a key step in any successful emergency fund guide.
Step 6: Boost Your Fund with Extra Income
Accelerating your emergency fund growth can be achieved by generating extra income. This proactive emergency fund guide encourages exploring various avenues to earn more. Every additional dollar you earn can be directly funneled into your savings, shortening the time it takes to reach your goal. Consequently, this step is powerful in knowing how to build emergency fund quickly.
Strategies for Increasing Your Income
Consider taking on a side hustle, selling unused items, or picking up extra shifts at work. Even small amounts from freelancing or odd jobs can make a big difference. For instance, a garage sale can clear clutter and add cash to your fund. Our emergency fund guide suggests thinking creatively about your skills and resources. Dedicate any windfalls, like tax refunds or bonuses, to your emergency fund as well. These efforts greatly contribute to your emergency fund guide progress.
Step 7: Revisit and Replenish Your Emergency Fund Guide
Building an emergency fund is not a one-time event; it’s an ongoing process. Periodically review your fund to ensure it still meets your needs. This thoughtful emergency fund guide recommends annual check-ups. Life changes, and so should your financial safety net. If you dip into your fund, make replenishing it your top financial priority. Understanding this continuous cycle is crucial for sustained financial security, as advised by this emergency fund guide.
Maintaining and Adjusting Your Fund Over Time
Your essential expenses might increase due to inflation, new family members, or a change in living costs. Adjust your target amount accordingly. If you use part of your emergency fund for an actual emergency, immediately start rebuilding it. Treat this replenishment with the same urgency as initial savings. This proactive approach ensures your emergency fund guide remains a reliable shield against future financial shocks. For more information on securing your car and auto finance guides, visit our articles.
Action Plan: How to Build Emergency Fund Effectively
- Month 1: Define Target & Automate First Deposit. Calculate 3-6 months of essential expenses. Set up an automatic transfer of at least $50 to a HYSA.
- Month 2: Budget Optimization. Review spending from the past month, identify 2-3 areas for cuts (e.g., eating out less, canceled subscriptions). Redirect saved money to your fund.
- Month 3: Boost with Found Money. Sell unused items online or have a garage sale. Apply any tax refunds or bonuses directly to your emergency fund guide.
- Month 4-6: Increase Contributions. As you get comfortable, increase your automated deposit by $25-$50. Re-evaluate your budget for further savings opportunities.
- Ongoing: Monitor & Adjust. Annually review your essential expenses and financial goals. Replenish any used funds immediately.
- Long-Term Goal (Ongoing): Aim for 6 months of expenses, then consider additional savings for specific large unexpected events. The emergency fund guide is a living document.
Conclusion: Securing Your Future with an Emergency Fund Guide
Building an emergency fund is a cornerstone of sound personal finance. By following these 7 steps, you are well on your way to creating a robust financial safety net. This comprehensive emergency fund guide empowers you to tackle unexpected expenses without derailing your financial progress. Remember, consistency and discipline are key. Start today, and secure your financial peace of mind. Your future self will certainly thank you for following this emergency fund guide diligently. Moreover, knowing how to build emergency fund provides undeniable confidence.
FAQs About Your Emergency Fund Guide
How much should be in my emergency fund?
Most financial experts recommend having 3 to 6 months’ worth of essential living expenses saved in your emergency fund guide. This provides a solid buffer against unexpected financial setbacks.
Where should I keep my emergency fund?
Your emergency fund guide should ideally be kept in a high-yield savings account (HYSA). This offers easy access to your money while earning more interest than a traditional savings account, keeping your funds liquid and growing.