Smart Ways to Invest $1,000 for Growth in 2026
Got $1,000 to invest in 2026? That’s a solid starting point to grow your money, but only if you choose the right strategy. The investing landscape changes fast, and what worked in 2020 might not be your best bet today. Whether you’re saving for retirement, building an emergency fund, or aiming for short-term gains, we’ve broken down the smartest ways to put that $1,000 to work. Here’s how to make every dollar count.
1. High-Yield Savings Accounts (HYSA) for Safety First
Real talk: If you might need that $1,000 within the next year, don’t gamble it in the stock market. A high-yield savings account (HYSA) is your safest bet. In 2026, top HYSAs offer between 4.5% and 5.2% APY, far outpacing traditional savings accounts. For example, a $1,000 deposit at 5% APY earns you $50 in a year with zero risk.
- Pros: FDIC insured, instant access to cash, no fees at most online banks
- Cons: Lower returns than stocks or crypto over time
- Best for: Emergency funds or short-term savings goals
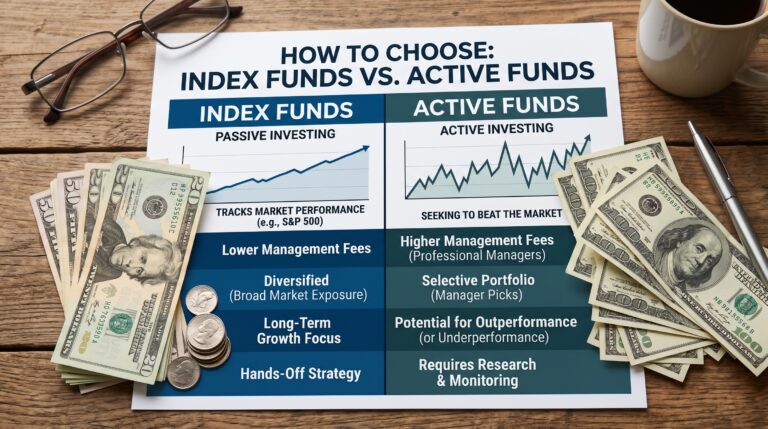
2. Index Funds: The Set-and-Forget Strategy
Here’s the thing: Most people don’t beat the market, so why try? Index funds let you own a tiny slice of hundreds of companies with minimal fees. In 2026, the S&P 500 has averaged 7-9% annual returns over the past decade. A $1,000 investment in an S&P 500 index fund like VFIAX could grow to around $1,800 in 10 years without adding another dime.
Want even broader exposure? Consider a total stock market fund like VTSAX. These funds automatically rebalance, so you don’t need to stress about picking individual stocks.
3. Roth IRA: Tax-Free Growth for Retirement
If you’re under 50 and earned less than $153,000 in 2026 (or $228,000 if married filing jointly), a Roth IRA is a golden opportunity. You contribute after-tax dollars now, but all future growth is tax-free. Let’s say you invest that $1,000 in a Roth IRA at age 30. With a 7% return, it could balloon to over $7,600 by age 65. And you won’t owe a penny in taxes when you withdraw.
Bonus: You can withdraw your contributions (but not earnings) anytime without penalties, making it more flexible than a traditional IRA.
4. Real Estate Crowdfunding for Passive Income
Don’t have enough for a down payment? Platforms like Fundrise and RealtyMogul let you invest in real estate with as little as $500. In 2026, these platforms average 8-12% annual returns through rental income and property appreciation. Your $1,000 could generate $80-$120 per year in passive income while diversifying your portfolio beyond stocks.
Just remember: These investments typically require 5+ years to see substantial returns, and some charge fees around 1% annually.
5. Crypto: High Risk, Potential High Reward
Bottom line: Only invest what you can afford to lose. Bitcoin and Ethereum have shown volatility but delivered massive gains over long periods. In 2026, crypto experts suggest allocating no more than 5-10% of your portfolio to digital assets. A $1,000 investment split between Bitcoin (50%), Ethereum (30%), and stablecoins (20%) balances growth potential with some stability.
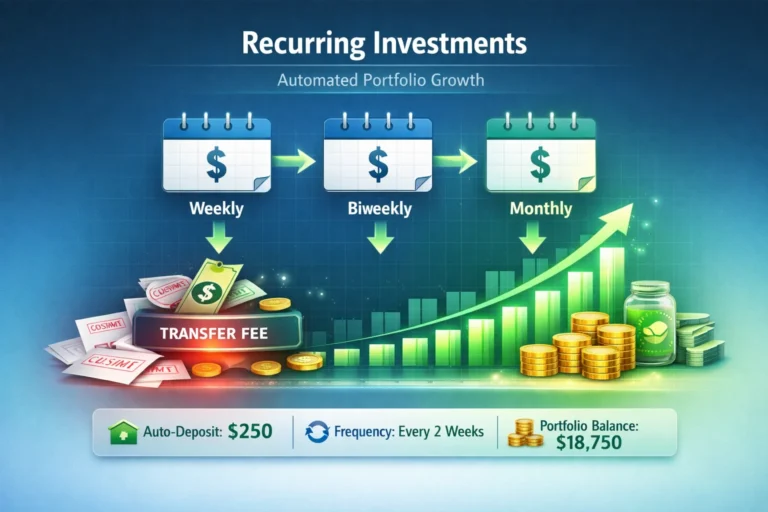
Pro tip: Use dollar-cost averaging. Instead of dropping $1,000 all at once, invest $100 weekly over 10 weeks to smooth out price swings.
Frequently Asked Questions
Should I invest $1,000 all at once or gradually?
Statistically, lump-sum investing beats dollar-cost averaging about 67% of the time. But if market swings keep you up at night, spreading investments over 3-6 months can ease anxiety. For most people in 2026, we recommend investing the full $1,000 immediately in diversified assets.
How much will $1,000 grow in 10 years?
At a 7% annual return (stock market average), your $1,000 becomes about $1,967. At 10% (possible with growth stocks or real estate), it jumps to $2,594. Use compound interest calculators to play with different scenarios.
What’s the safest way to invest $1,000?
Series I Savings Bonds from the U.S. Treasury currently yield 4.3% with inflation protection. They’re backed by the government and perfect for ultra-conservative investors. The catch? You can’t cash out for at least one year.
Can I start investing with less than $1,000?
Absolutely. Many brokerages like Fidelity and Charles Schwab now offer $0 minimums and fractional shares. You can buy a slice of Amazon or Tesla with just $5. Start small, but start today.
Ready to make your $1,000 work harder? Pick one strategy from this list that aligns with your goals and risk tolerance, then take action this week. The biggest mistake isn’t choosing the “wrong” investment, it’s letting your money sit idle. Compound interest rewards those who start early, so don’t wait for the “perfect” moment. Your future self will thank you.